Terms & Conditions
Legal Considerations
This presentation (this “Presentation”) is being furnished upon your request on a confidential basis solely for informational purposes and may not be reproduced or provided to others without the prior written consent of Warburg Pincus LLC (together with certain of its affiliates, “WP”, “Warburg”, “Warburg Pincus” or the “firm”). By accepting delivery of this Presentation, each recipient agrees to the foregoing and that it will cause its representatives and advisors to so agree. This Presentation does not constitute an offer to sell, or a solicitation of an offer to buy, an interest in any security or Warburg Pincus private equity fund or other investment vehicle (each, a “Warburg Pincus Fund”). The information set forth herein does not purport to be complete and is subject to change. The firm has no responsibility to update any of the information provided in this Presentation. An investment in a Warburg Pincus Fund may only be made on the basis of the information contained in the confidential private placement memorandum of such Warburg Pincus Fund (the “Memorandum”), as and when available, which will describe certain risks related to an investment in the Warburg Pincus Fund and other important information about the Warburg Pincus Fund.
By accepting this Presentation, the recipient agrees that the recipient will, and will cause the recipient’s representatives and advisors to, use the Presentation, as well as any information derived by the recipient from the Presentation, only for the evaluation of the performance of the Warburg Pincus Funds and the Warburg Pincus Funds’ investments and for no other purpose.
Neither Warburg Pincus, any Warburg Pincus Fund nor any of their respective affiliates makes any representation or warranty, express or implied, with respect to the fairness, correctness, accuracy, reasonableness or completeness of any of the information contained herein (including but not limited to economic, market or other information obtained from third parties and the sponsors or managers of prior investments included herein), and each expressly disclaims any responsibility or liability therefor.
The recipient acknowledges and agrees that the recipient is a sophisticated investor with such knowledge and experience in financial and business matters as to be capable of evaluating the merits and risks of the opportunities described herein, and shall independently and without reliance upon Warburg Pincus, make its own appraisal of, and investigation into the business, operations, property, financial and other conditions, creditworthiness, likelihood of success, merits and consequences of the opportunities described herein.
The Presentation is based upon information reasonably available to Warburg Pincus as of the date hereof. The delivery of this Presentation shall not, under any circumstances, create any implication that the Presentation is correct in all respects, including as of any time subsequent to the date hereof, and Warburg Pincus does not undertake any obligation to update such information at any time after such date. Certain of the information contained herein, particularly in respect of market data, economic and other forecasts and performance data, has been obtained from third-party sources. While Warburg Pincus believes such sources to be reliable, none of Warburg Pincus, any Warburg Pincus Fund or their respective affiliates has updated any such information through the date hereof or undertaken any independent review of such information.
Historical return information in this Presentation is not necessarily indicative of future performance. Investments in private equity do not have the same diversification and liquidity profiles as the indices selected for general comparison purposes. This Presentation also includes pro forma values and forward-looking statements, which are inherently uncertain and based on assumptions that could change as a result of a portfolio company’s operating performance, capital markets risks and general economic conditions. Unless otherwise indicated, financial information is as of June 30, 2026, and Warburg Pincus Funds or individual portfolio companies may have experienced, in certain instances, negative performance since such date. There can be no assurance that future Warburg Pincus Funds or individual portfolio companies will achieve comparable results as those presented herein or will be able to implement their investment strategies or achieve their investment objectives. Investments in private equity are speculative and risk the loss of capital.
The firm’s companion, continuation, sponsor-led secondary, real estate, long-term investment and capital solutions funds, including (i) WPVI, WPIP, WPE, WPC, WPFS, WPC-SEA II, WPFS II and WPFS III, (ii) WP XI (Asia), WP AUSA, WP AUSA I-A, WP DVT and WP Jovian, (iii) each of WPRE and WPARE, (iv) WP Dynasty, and (v) WPCS FF are, except where otherwise indicated, generally excluded from the discussions and statements in this Presentation regarding aggregate performance and fundraising (although the effect of the sale of certain assets to WP XI (Asia), WP AUSA, WP AUSA I-A, WP DVT, WP Jovian and WP Dynasty are reflected in the performance of WP XI, WP XII, WP China WPFS and/or WPGG, as applicable). The Companion Funds have a more narrow investment strategy and scope and have less diversified and more concentrated investment portfolio, the continuation and sponsor-led secondary funds are not blind-pool funds, WPRE and WPARE are real estate funds, WP Dynasty is a long-term investment vehicle established to acquire “new economy” real estate companies across Asia-Pacific and WPCS FF is an investment fund which targets portfolio investments with lower target and dispersion of return profiles and different structural protections than any Warburg Pincus Fund, and, in each case, do not have substantially similar investment policies, objectives and strategies to any Warburg Pincus Fund, and accordingly Warburg Pincus does not believe that they are relevant for aggregate performance purposes. Except in the case of certain investments in “Alternative Financial Sector Opportunities” made by WPFS, all investments made by a Companion Fund were also investments of one or more Global Funds. For the avoidance of doubt, references herein to Private Equity Funds include only Global Funds and Companion Funds and exclude Warburg Pincus continuation, sponsor-led secondary, real estate, long-term investment and capital solutions funds.
Statements contained in this Presentation (including those relating to current and future market conditions and trends in respect thereof) that are not historical facts are based on current expectations, estimates, projections, opinions and/or beliefs of Warburg Pincus. Such statements involve known and unknown risks, uncertainties and other factors, and undue reliance should not be placed thereon. In addition, no representation or warranty is made with respect to the reasonableness of any estimates, forecasts, illustrations, prospects or returns, which should be regarded as illustrative only, or that any profits will be realized. Certain information contained herein constitutes “forward-looking statements” that relate to, among other things, recent and active prior Warburg Pincus funds and to the financial environment in which any Warburg Pincus Fund will operate, which can be identified by the use of forward-looking terminology such as “may,” “will,” “should,” “expect,” anticipate,” “project,” “estimate,” “intend,” “continue,” “target,” or “believe” or the negatives thereof or other variations thereon or comparable terminology. Furthermore, any projections or other estimates in this Presentation, including estimates of returns or performance, are “forward-looking” statements and are based upon certain assumptions that may change. Prospective investors should be aware that these statements are estimates or expectations, reflecting only the judgment of Warburg Pincus. Actual results and events could differ materially from those contemplated by these forward-looking statements as a result of various risks and uncertainties , actual events or results or actual performance of any Warburg Pincus Fund may differ materially from those reflected or contemplated in such forward-looking statements. Moreover, actual events are difficult to project and often depend upon factors that are beyond the control of Warburg Pincus and its affiliates. Warburg Pincus does not undertake any obligation to update or revise the forward-looking statements contained in this Presentation to reflect events or circumstances occurring after the date of this Presentation or to reflect the occurrence of unanticipated events. No representation or warranty is made as to future performance or such forward looking statements.
Any discussion and/or inclusion of pipeline investments is for illustrative purposes only. These investments are not subject to a letter of intent, memorandum of understanding or any other binding obligation of Warburg Pincus or any Warburg Pincus Fund to make these investments. Nothing herein should be relied upon as a promise or representation as to potential investments by Warburg Pincus or any Warburg Pincus Fund. No assurance can be given that any such pipeline transaction will be allocated to or consummated by Warburg Pincus or any Warburg Pincus Fund or, if any such transaction is consummated, that Warburg Pincus or any Warburg Pincus Fund will be able to implement its business plans with respect to such investment or that such investment will perform to expectations.
Actual returns on unrealized or partially realized investments described herein will depend on, among other factors, future operating results, the value of the assets and market conditions at the time of disposition, legal and contractual restrictions on transfer that may limit liquidity, any related transaction costs or taxes and the timing and manner of sale, all of which may differ from the assumptions and circumstances on which the valuations used in the prior performance data contained herein are based. Accordingly, the actual realized returns on unrealized or partially realized investments may differ materially from the returns indicated herein. There can be no assurance that historical trends will continue. Case studies presented herein are for illustrative purposes only, have been selected in order to provide examples of the types of investments made by the firm and do not purport to be a complete list thereof. Case studies are compiled to illustrate the broad industry knowledge, geographic reach and multiple stages of development in which Warburg Pincus invests. It should not be assumed that investments made in the future will be comparable in quality or performance to the investments described herein. Further, references to the investments included in the illustrative case studies should not be construed as a recommendation of any particular investment or security. Warburg Pincus’ valuations of unrealized investments shown herein are based on assumptions that Warburg Pincus believes are reasonable under the circumstances, although actual realized returns will depend on factors such as market conditions, future operating results, the value of the assets at the time of disposition, any related transaction costs and the timing and manner of sale, all of which may differ from the assumptions on which the unrealized values or returns are based. Certain information was provided by the companies and certain statements reflect the firm’s beliefs as of the date hereof based on prior experience and certain assumptions that the firm believes are reasonable, but may prove incorrect. A full list of the firm’s investments and track record is available upon request. Please see Important Disclosures and Notes to Performance for more important disclosures. Where forecasts are shown in this Presentation, actual results may be materially different from such forecasts presented. These assumptions should not be construed to be indicative of the actual events which will occur. Actual events are difficult to project and depend upon factors that are beyond the control of Warburg Pincus or its respective affiliates, members, partners, stockholders, managers, directors, officers, employees and agents. Other events which were not taken into account, including general economic factors which are not predictable, may occur and may significantly affect the actual returns or performance of a fund and/or any of the companies in which a fund has invested. The recipient acknowledges that it is aware that federal and state securities laws prohibit any person who has material, non-public information about a company from purchasing or selling securities of such a company or from communicating such information to any other person under circumstances in which it is reasonably foreseeable that such person is likely to purchase or sell such securities. The inclusion of any third party logos herein does not reflect an endorsement by the entity whose logo is so included nor does it represent or imply any affiliation with such entity.
Sustainability Strategy (“Sustainability”) goals are aspirational and not guarantees or promises that all goals will be met. Statistics and metrics relating to Sustainability matters are estimates and may be based on assumptions or developing standards (including Warburg Pincus’ internal standards and policies), There can be no assurance that Warburg Pincus’ Sustainability policies and procedures as described herein will continue throughout the life of any Warburg Pincus Fund and Warburg Pincus’ Sustainability policies and procedures could change, even materially. Warburg Pincus is permitted to determine in its discretion that it is not feasible or practical to implement or complete certain of its Sustainability initiatives based on cost, timing or other considerations. Sustainability factors are only some of the many factors Warburg Pincus considers in making an investment, and there is no guarantee that Warburg Pincus will make investments in companies that create positive ESG impact or that consideration of Sustainability factors will enhance long-term value and financial returns for limited partners. To the extent Warburg Pincus engages with portfolio companies on ESG-related practices and potential enhancements thereto, there is no guarantee that such engagements will improve the financial or Sustainability performance of the investment.
None of the information contained herein has been filed with the U.S. Securities and Exchange Commission, any securities administrator under any securities laws of any U.S. or non-U.S. jurisdiction or any other U.S. or non-U.S. governmental or self-regulatory authority. No such governmental or self-regulatory authority will pass on the merits of the offering of interests in any Fund or the adequacy of the information contained herein. Any representation to the contrary is unlawful.
Important Information to UK / Swiss / EEA recipients
No interest in any fund vehicle will be offered pursuant to this document and any information provided with respect to any fund vehicle in this document is provided for information purposes only.
In relation to any recipient domiciled or having a registered office (or whose decision to invest in the fund will be made for or on behalf of such investors by a person that is domiciled, or with a registered office) in the European Economic Area (the “EEA”) or in the United Kingdom (the “UK”) (an “EEA/UK Investor”), this presentation is provided only to investors which are “professional investors” for the purposes of Directive 2011/61/EU of the European Parliament and of the Council dated 8 June 2011 on Alternative Investment Fund Managers, as implemented in any relevant jurisdiction, together with Commission Delegated Regulation (EU) No 231/2013, as well as any similar or supplementary law, rule or regulation, in each case as amended from time to time, including as implemented in the UK pursuant to applicable legislation including the UK Alternative Investment Fund Managers Regulations 2013/1773, and retained and amended from time to time (“AIFMD”) and professional clients for the purposes of the Markets in Financial Instruments Directive 2014/65/EU (as amended) and all implementing and related legislation, as implemented in each member state of the European Economic Area (“EEA”) and as implemented and retained by the UK following its departure from the European Union (“MiFID II”) and Regulation 1286/2014/EU on Packaged Retail and Insurance-based Investment Products, each as amended from time to time and as implemented into the law of each relevant member state of the EEA and as implemented and retained by the UK following its departure from the European Union (“PRIIPs Regulation”). As such, no PRIIPs Key Information Document (KID) (as defined in the PRIIPs Regulation) will be prepared in respect of any product referred to herein.
In the UK, this presentation is being distributed only to and is directed only at, as applicable: (i) persons who have professional experience in matters relating to investments falling within Article 19(5) of the Financial Services and Markets Act 2000 (Financial Promotion) Order 2005 (as amended) (the “FP Order”), (ii) persons falling within one of the categories of “investment professionals” as defined in Article 14 of the Financial Services and Markets Act 2000 (Promotion Of Collective Investment Schemes) (Exemptions) Order 2001 (as amended) (the “PCIS Order”), (iii) persons falling within any categories of persons described in Article 22 of the PCIS Order, (iv) high net worth entities falling within Article 49(2) of the Order, or (v) any other persons to whom it may otherwise lawfully be communicated (all such persons together being referred to as “Relevant Persons”). Persons who are not Relevant Persons must not act on or rely on this presentation or any of its contents. Any investment or investment activity to which this presentation relates is available only to Relevant Persons and will be engaged in only with Relevant Persons. Recipients must not distribute, publish, reproduce or disclose this Presentation, in whole or in part, to any other person. No person falling outside the category of Relevant Persons should treat this Presentation as constituting an invitation, inducement or promotion to such person.
In relation to any recipient domiciled or having a registered office (or whose decision to invest in the fund will be made for or on behalf of such investors by a person that is domiciled, or with a registered office) in Switzerland, this presentation is provided only to investors which are qualified investors, as defined in art. 10 para. 3 of the Collective Investment Schemes Act dated June 23, 2006 (as amended) (“CISA”). A Warburg Pincus fund or investment vehicle can only be offered to institutional and professional investors within the meaning of art. 4 para. 3 and 4 and art. 4 para. 5 of the Swiss Federal Act on Financial Services of 15 June 2018, as amended (“FinSA”). An investment in the relevant Warburg Pincus fund or investment vehicle is therefore only available to, and any advertising is only directed at, institutional and per-se professional investors (excluding opting-out retail investors) according to FinSA. No Swiss representative and paying agent have been appointed for any Warburg Pincus fund or investment vehicle. Therefore, investors do not benefit from protection under the CISA or from supervision by the Swiss Financial Market Supervisory Authority (“FINMA”) and an investment in a Warburg Pincus fund or investment vehicle may carry higher levels of risk.
Each investment vehicle of a fund may be subject to different regulatory requirements, including for pre-marketing and marketing purposes. The ability to participate in any investment vehicle may be subject to regulatory requirements or restrictions in the applicable jurisdictions and participation in a particular investment vehicle may not be available to all investors.
Important Disclosures and Notes to Performance Information
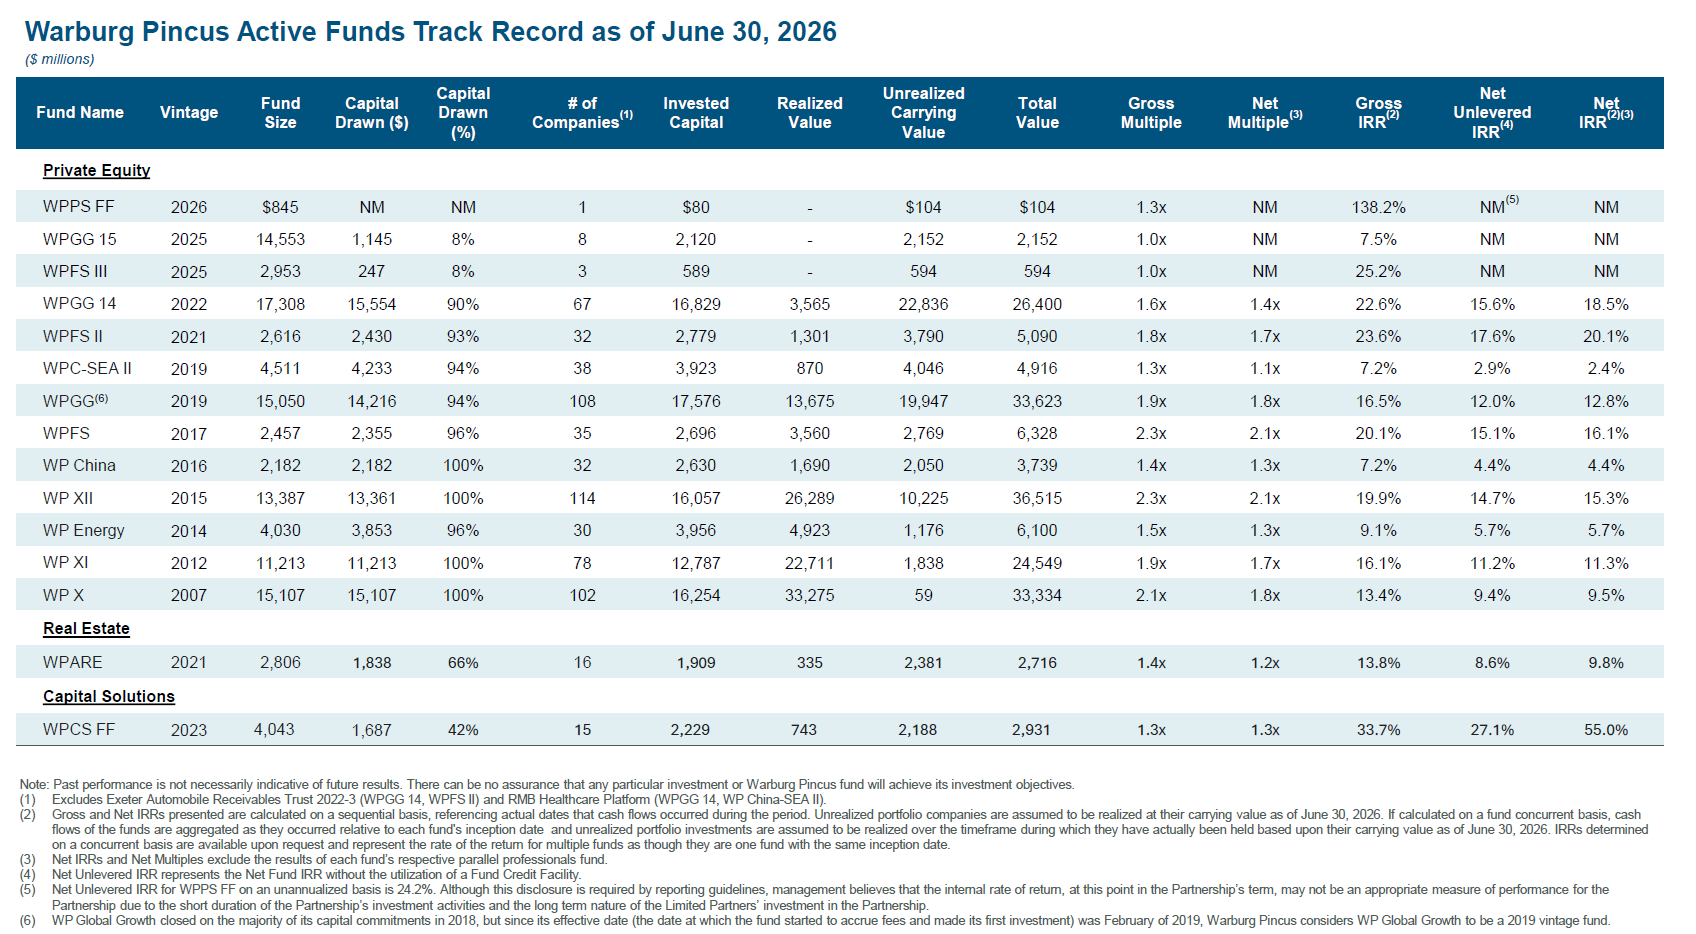
Gross IRRs and gross Investment Multiples presented throughout this Presentation are calculated before fund-level fees, expenses and carried interest, which would reduce returns to an investor. Net IRRs, unlevered net IRRs, net Investment Multiples and net Fund Multiples reflect the effects of fees, expenses and carried interest. Past performance can provide no assurance of future results, and there can be no assurance that any Warburg Pincus Fund will achieve comparable results, that returns generated by any Warburg Pincus Fund will equal or exceed those of other investment activities of Warburg Pincus or that any Warburg Pincus Fund will be able to implement its investment strategy and approach or achieve its investment objectives. Certain aggregate returns shown herein reflect aggregate performance across multiple Private Equity Funds which were not managed as a single fund or portfolio, with investments that were made over a long period of time and over the course of various market and macroeconomic circumstances. These circumstances may have differed from those applicable to any Warburg Pincus Fund.
For purposes of this Presentation, with respect to Private Equity Funds (i) “Completed” refers to Private Equity Funds which Warburg Pincus believes have finished investing and have distributed substantially all proceeds to such funds’ investors or are in liquidating trusts (i.e., EMW Ventures, WPA, WPCP, WPCC, WPI, WP Ventures, WPVI, WPEP, WPIP, WP VIII and WP IX), (ii) “Mature” refers to Private Equity Funds which Warburg Pincus believes have primarily finished investing and have distributed (including any write-offs) an amount in excess of such funds’ paid-in-capital but which are still in the process of realizing proceeds from the net asset value of such funds (i.e., WP X and WP XI), (iii) “Recent” refers to Private Equity Funds which have completed their investment period and/or are no longer making new portfolio investments but are early in the process of realizing proceeds (i.e., WPE, WP XII, WPC, WPFS and WPGG) and (iv) “Active” refers to Private Equity Funds which are actively making new portfolio investments (i.e., WPC-SEA II, WPFS II and WPGG 14).
Gross IRRs, net IRRs, unlevered net IRRs and gross and net Multiples include the value of unrealized investments. Actual returns on unrealized investments described herein will depend on, among other factors, future operating results, the value of the assets and market conditions at the time of disposition, legal and contractual restrictions on transfer that may limit liquidity, any related transaction costs or taxes and the timing and manner of sale, all of which may differ from the assumptions and circumstances on which the valuations used in the prior performance data contained herein are based. Accordingly, the actual realized returns on unrealized investments may differ materially from the returns indicated herein. Prospective investors should review carefully the notes and other qualifying information accompanying the performance information throughout this Presentation.
Net investment performance herein is generally shown in respect of limited partners in the aggregate at the applicable fund- or funds-level; however, net investment performance for subsets of investments are estimated (as hereinafter described). The performance of an individual investor in a fund may also differ from fund-level returns due to factors including: (i) the timing of an investor’s capital contributions, including as a result of a later subscription and related charges or, for performance measures other than unlevered net IRR, the fund’s use of borrowing, (ii) various structuring elections, including the use of one or more blocker entities on a particular transaction that were not common to all investors or other tax determinations, (iii) differences in fees or expenses allocable to certain investors as a result of fee rebates, taxes or other considerations, including fee discounts or reduced carried interest and (iv) the excuse or exclusion of an investor for one or more of such fund’s investments. Accordingly, no investor, even if participating in a fund, necessarily achieved the exact net IRR, net Investment Multiple or net Fund Multiple shown.
The investment-level performance of investments held for a period of less than one year has been annualized for purposes of inclusion in performance presentation of this Presentation. Such annualized performance represents an estimate, and actual performance of any such investment will likely differ, even materially, from such estimate.
“Gross profits” are presented on a “gross” basis (i.e., they do not reflect management or other fees, expenses and carried interest, which will reduce returns and, in the aggregate, are expected to be substantial).
For purposes of this Presentation, loss ratios are defined as the ratio of realized and unrealized write-downs and write-offs to total dollars of invested capital in the relevant set of investments to date.
Valuation Methodology
Except as otherwise noted in this Presentation, IRRs, Multiples and total returns include realized investments and the value of unrealized investments. Investments held at June 30, 2026 are valued at their carrying value in accordance with the relevant fund’s U.S. GAAP financial statements as of that date giving effect to ASC 820 “Fair Value Measurement.” In the absence of special circumstances, all portfolio investments are valued at fair value. Fair value for publicly traded portfolio investments is determined based on the closing price of the underlying public security on the exchange that the security is principally traded. Privately held warrants on publicly traded portfolio investments are valued at fair value using various methods including option pricing models such as Black-Scholes. The fair value depends upon the contractual terms of the warrants, as well as the availability of observable inputs. Such inputs include the market value of the referenced public securities, measures of volatility (historic volatility of the referenced public securities and/or the implied volatility of comparable publicly traded options) and correlations of such inputs. Restricted and privately held portfolio investments, which may not have readily ascertainable market values, are valued at fair value, which is the estimated amount that would be received in a sale of the portfolio investment in an orderly transaction between willing market participants at the measurement date. Generally, the fair value of private investments is adjusted when a significant third-party investment or financing event has occurred or there is a significant change in the financial condition or operating performance of the portfolio investment which would indicate either an increase or decrease in fair value. Various valuation techniques and inputs are considered in valuing private portfolio investments, including purchase multiples paid in other comparable third-party transactions, comparable public company trading multiples, discounted cash flow analysis, market conditions, liquidity, current operating results and other pertinent information. When utilizing a multiples-based approach, multiples are applied to the most recent and relevant operating performance metrics of the portfolio investment as appropriate, including historical and/or forecasted revenue, EBITDA, production reserves, net income or other relevant operating performance metrics. Consideration is also given to exchange rate fluctuations for investments denominated in foreign currencies. However, because of the inherent uncertainty of valuation, the carrying values may differ significantly from values that would have been used had a ready market for the restricted and privately held portfolio investments existed and may differ significantly from the amounts realized upon disposition, and the differences could be material.
Warburg Pincus’ valuations of unrealized investments are based on assumptions that Warburg Pincus believes are reasonable under the circumstances, although actual realized returns will depend on factors such as market conditions, future operating results, the value of the assets at the time of disposition, any related transaction costs or taxes and the timing and manner of sale, all of which may differ from the assumptions on which the unrealized values or returns are based. Accordingly, no assurance can be given that unrealized valuations or returns will be achieved and the actual realized return of unrealized investments may differ materially from the returns indicated herein. Summary statements of Warburg Pincus’ investment performance, as well as references to “Invested Capital”, unless otherwise indicated, include the total amount invested across all applicable Warburg Pincus funds.
Calculation of Gross and Net IRRs
Gross IRRs for Private Equity Funds are calculated based upon the actual dates of cash outflows from a fund to make investments in portfolio investments and cash inflows to a fund prior to deductions for blocker-level taxes and expenses, if any, from realization events such as dispositions of securities in portfolio investments or distributions made by such portfolio investments. The value associated with the realization is the U.S. dollar equivalent of cash consideration as and when received or in the case of a distribution in kind, the realized value is determined based upon the valuation methodology determined under the limited partnership agreement for the relevant Warburg Pincus fund that distributed the securities. The valuation of in-kind distributions is determined based upon the closing price on the date of distribution for EMW Ventures, WPA, WPCP, WPCC and WPI. For WP Ventures, WPVI and WPEP, distributions in kind are valued based upon the average closing price on the 20 trading days subsequent to the date of the distribution. For WPIP, WP VIII, WP IX, WP X, WP XI, WPE, WP XII, WPC, WPFS, WPGG, WPC-SEA II, WPFS II and WPGG 14, distributions in kind are valued based upon the average closing price on the ten trading days commencing with the date of the distribution. Unrealized portfolio investments are assumed to be realized at their carrying value as of June 30, 2026, as described above under “Valuation Methodology.”
Net IRRs for Warburg Pincus funds are calculated based upon the actual due dates of capital call payments by Limited Partners to the funds and the actual distributions, net of fees, expenses and carried interest, from the funds to Limited Partners as of the dates they occurred and the remaining net asset value, if any, attributable to the Limited Partners as determined for each fund as of June 30, 2026. Because net IRRs are based on the dates of contribution by Limited Partners rather than the dates of fund investments, the use of credit facilities in certain circumstances has the effect of increasing the reported net IRR of a fund.
Unlevered net IRRs for Warburg Pincus funds utilize the same assumptions as net IRRs, except that they are calculated based upon the dates the funds received cash from credit facility drawdowns, and the dates the funds made credit facility repayments. Interest expenses associated with credit facilities borne by the funds are treated as capital distributions and the net asset value as of the end of each quarter is adjusted for the relevant borrowing amount.
As described above, distributions in kind are valued as per the methodologies set forth in the relevant fund agreements. The net asset value represents the fair value of the fund’s portfolio investments and cash and other assets less its liabilities. The net asset value for each fund as of June 30, 2026 is determined after all fees, expenses and unrealized carried interest have been allocated.
There are a number of factors that can impact the difference between gross IRRs on one hand, and net IRRs and unlevered net IRRs on the other hand. These include carried interest, fees and expenses, the timing of capital calls versus investments, the timing of distributions versus realizations from portfolio investments and the amount, timing and investment performance associated with recycling realized proceeds. The difference between gross and net Multiples is impacted by all of the same factors except timing.(1)
As with all performance data, past performance can provide no assurance of future results.
IRR Aggregation Methods
For aggregate gross and net IRRs, aggregate gross Investment Multiples, net Fund Multiples and net Investment Multiples and distribution information based on investments made by separate funds, no single investor necessarily participated in each of such funds and/or invested the necessary amounts in any such fund so as to result in the returns and/or distributions described in this Presentation. Aggregate IRRs for more than one fund are generally computed on a sequential cash flow basis.
Sequential Cash Flow Basis. Unless otherwise indicated for the purpose of presenting IRRs over time in order to compare returns of multiple Warburg Pincus funds or investments from multiple funds to an index, as well as IRRs with respect to investment performance attributed to certain Warburg Pincus investment professionals, IRRs are based upon the actual dates that cash flows of the fund to or from the portfolio investments occurred during the period presented. Unrealized portfolio investments are assumed to be realized at their carrying value as of June 30, 2026, as described above.
Fund Concurrent Basis. For calculations on a fund concurrent basis, the IRRs for multiple funds were calculated by aggregating the cash flows as they occurred relative to each fund’s inception date and determining the resulting IRR as though they were one fund with the same inception date. Unrealized portfolio investments are assumed to be realized after a timeframe equal to their actual holding period based upon their carrying value as of June 30, 2026, as described above.
(1) The use of subscription-based credit facilities generally will result in a higher reported IRR than if such facility had not been utilized. Warburg Pincus utilizes a multi-fund hybrid credit facilities with both subscription- and NAV-based borrowings. Warburg Pincus has historically drawn down capital on the credit facilities for limited periods, therefore the impact on IRR would not be material.
Calculation of Gross Investment Multiples and Net Fund Multiples
Gross Investment Multiple is calculated to reflect the gross return on one or more portfolio investments as a multiple of the total amount invested in such investments by the applicable funds. Gross Investment Multiple reflects the total realized proceeds to the applicable fund and the remaining carrying value of such portfolio investment divided by the total cost of such portfolio investment.
Net Fund Multiples are calculated to reflect the net return on investment to Limited Partners. Distributions to paid-in capital (“DPI”) reflect the dollars distributed from a fund to its Limited Partners divided by the amount of capital paid into the fund by such Limited Partners. Remaining value to paid-in capital (“RVPI”) reflects the amount of a fund’s remaining net asset value attributable to its Limited Partners (after all fees, expenses and carried interest allocations as of June 30, 2026) divided by the amount of capital paid into the fund. Total value to paid-in capital (“TVPI”) reflects the sum of dollars distributed from a fund to its Limited Partners and the amount of a fund’s remaining net asset value attributable its Limited Partners divided by the amount of capital paid into the fund by such Limited Partners. The sum of DPI and RVPI is equal to TVPI. Net Fund Multiples as presented in this Presentation are equal to TVPI and is net of recycled capital (i.e., the denominator used to calculate Net Fund Multiples only reflects the amount of capital called from Limited Partners and does not include amounts that have been recalled from the proceeds distributed or retained from the proceeds available for distribution to Limited Partners).
As with all performance data, past performance can provide no assurance of future results.
Calculation of Estimated Net IRRs, Estimated Net Unlevered IRRs and Estimated Net Investment Multiples (Private Equity Funds)
Estimated net IRRs and net Multiples are estimated to reflect fees, expenses and carried interest, as further explained below. Exact net returns which reflect portfolio investments or subsets of such investments and the circumstances pertaining thereto cannot be calculated due to the lack of a mechanism to properly allocate the relevant portions of aggregate fees, expenses and carried interest to each investment or to such investments collectively as a subset of investments made by different funds, as net returns can only be calculated on an exact basis for each fund. Except as with respect to negative performance figures, net unlevered IRRs are estimated to be 75% of gross IRR on a sequential cash flow basis and estimated net Investment Multiples are estimated to be 90% of gross Investment Multiples for individual portfolio investments. Warburg Pincus estimated net unlevered IRR and estimated net Investment Multiple for subsets of portfolio investments are estimated as the midpoint of the range of the net IRR to gross IRR (72.5-77.5%) and net Fund Multiple to gross Investment Multiple (85-95%) ratios of actual and expected performance of the three most recent Global Funds (WP XII, WPGG and WPGG 14) with broadly similar economic terms. Estimated net IRRs and estimated net Investment Multiples for performance figures, either for a single portfolio investment or subset, that have a gross performance of 0% or 1.0x, as applicable, or below, are presented as the same value as the gross presentation. Investments which have been permanently written off will be presented with an estimated net IRR and an estimated net Investment Multiple of (100%) and 0.0x, as applicable, provided the investment is more than one year old. In the rare event when investments are held less than a year and the IRR is incalculable (for example, when an investment is made on the last day of a quarter), both gross and estimated net IRR will be noted as “NM” with both gross Investment Multiples and estimated net Investment Multiples marked as 1.0x. Estimates of net IRR and net Investment Multiples are hypothetical estimates for which a variety of assumptions have been made to simplify the presentation, and no individual investor has received such returns; as is the case with any performance model, there are significant limitations on the application and uses of hypothetical fees and expenses in calculating hypothetical performance returns, and there can be no assurance that actual fees and expenses applicable to any Warburg Pincus Fund or any particular investor will reflect the hypothetical assumptions presented herein. Actual returns may differ materially from any hypothetical returns presented herein. The ratio of net unlevered IRR to gross IRR for the firm’s three most recent Global Funds (WP XII, WPGG and WPGG 14) may differ from the estimates used. Warburg Pincus believes that it is reasonable to evaluate the performance information included herein using the methods and assumptions described herein. However, there is no guarantee that such ratio will be the same or even a similar ratio of the net returns to gross returns of any Warburg Pincus Fund given that there are a number of factors that can impact the difference between gross and net returns of any Warburg Pincus Fund and those of the Private Equity Funds, and such factors and items related thereto may be different as between the Private Equity Funds to which the foregoing ratio so relates and any Warburg Pincus Fund.
In certain circumstances, except as with respect to negative performance figures, Warburg Pincus also calculates an estimated net IRR for the performance of subsets of portfolio investments. Such estimated net IRR is estimated to be 80% of gross IRR on a sequential cash flow basis. Such an estimate, like the ratio for estimated net unlevered IRR, is based on the ratio of levered net IRR to gross IRR for actual and expected performance of the three most recent Global Funds (WP XII, WPGG and WPGG 14) with broadly similar (i) economic terms and (ii) expected subscription credit facility usage.
As with all performance data, past performance can provide no assurance of future results.
Calculation of Estimated Net IRRs and Estimated Net Investment Multiples (WPARE II)
Estimated net IRRs and estimated net Investment Multiples are hypothetical and estimated to reflect fees, expenses and carried interest, as further explained below. Estimated Net Returns do not purport to present actual, historic performance for any specific portfolio investment or subset of such investments, rather, it seeks to illustrate how a historic investment or subset of such investments may have performed if such investment had been made by a fund with similar terms as WPARE II. Also note that exact net returns which reflect the exact historic performance of portfolio investments or subsets of such investments and the circumstances pertaining thereto cannot be calculated due to the lack of a mechanism to properly allocate the relevant portions of aggregate fees, expenses and carried interest to each investment or to such investments collectively as a subset of investments made by different funds, as net returns can only be calculated on an exact basis for each fund. Moreover, estimated net IRRs and estimated net Investment Multiples presented herein relate to Asia real estate investments, some of which were made by funds which did not have a real-estate focused investment strategy, and the terms of which may have differed, potentially materially, from WPARE II. Except as with respect to negative performance figures, estimated net IRRs are estimated to be 75% of gross IRR on a sequential cash flow basis and estimated net Investment Multiples are estimated to be 85% of gross Investment Multiples for individual portfolio investments. Warburg Pincus estimated such estimated net IRR and estimated net Investment Multiple for individual and subsets of portfolio investments by modelling the expected gross to net return differential of investments based on the Management Fees, carried interest, and recycling provisions of WPARE II, together with an estimated ratio of other fund-level expenses, excluding the cost of fund-level leverage. There is no guarantee that such ratio will be the same or even a similar ratio of the net returns to gross returns of WPARE II given that there are a number of factors that can impact the difference between gross and net returns of WPARE II. Estimated net IRRs and estimated net Investment Multiples for performance figures, either for a single portfolio investment or subset, that have a gross performance of 0% or 1.0x, as applicable, or below, are presented as the same value as the gross presentation. Investments which have been permanently written off will be presented with an estimated net IRR and an estimated net Investment Multiple of (100%) and 0.0x, as applicable, provided the investment is more than one year old. In the rare event when investments are held less than a year and the IRR is incalculable (for example, when an investment is made on the last day of a quarter), both gross and estimated net IRR will be noted as “NM” with both gross Investment Multiples and estimated net Investment Multiples marked as 1.0x. Estimates of net IRR and net Investment Multiples are hypothetical estimates for which a variety of assumptions have been made to simplify the presentation, and no individual investor has received such returns; as is the case with any performance model, there are significant limitations on the application and uses of hypothetical fees and expenses in calculating hypothetical performance returns, and there can be no assurance that actual fees and expenses applicable to WPARE II or any particular investor will reflect the hypothetical assumptions presented herein. Actual returns may differ materially from any hypothetical returns presented herein. Estimated net IRRs and estimated net Investment Multiples reflect an unlevered figure.
As with all performance data, past performance can provide no assurance of future results.
Calculation of Estimated Net IRR and Estimated Net Investment Multiples (WPCS FF)
Estimated net IRR for certain case studies, pipeline and passed on opportunities for WPCS FF are estimated as 84.0% of projected gross IRR, the midpoint of the range of estimated net IRR to estimated gross IRR ratios (81-87%) calculated based on a blended management fee and carried interest terms for all investors in the fund, plus expenses. Actual returns may differ materially based on a range of factors. Estimated net IRRs and estimated net Investment Multiples for performance figures that have a gross performance of 0% or 1.0x, as applicable, or below, are presented as the same value as the gross presentation. Investments which have been permanently written down will be presented with an estimated net IRR and an estimated net Investment Multiple of (100%) and 0.0x, as applicable, provided the investment is more than one year old. In the rare event when investments are held less than a year and the IRR is incalculable (for example, when an investment is made on the last day of a quarter), both gross and estimated net IRR will be noted as “NM” with both gross Investment Multiples and estimated net Investment Multiples marked as 1.0x.
Estimates of net IRR and net Investment Multiples are hypothetical estimates for which a variety of assumptions have been made to simplify the presentation, and no individual investor has received such returns; as is the case with any performance model, there are significant limitations on the application and uses of hypothetical fees and expenses in calculating hypothetical performance returns, and there can be no assurance that actual fees and expenses applicable to WPCS II or any particular investor will reflect the hypothetical assumptions presented herein, including due to differences in the terms of WPCS II as compared to the Private Equity Funds and differences in fees and expenses among investors in WPCS II. Actual returns may differ materially from any hypothetical returns presented herein. Additional information regarding the calculation of estimated net returns is available promptly upon request.
Ex-Discontinued Energy Investments
Certain performance information contained in this Presentation is presented on an Ex-Discontinued Energy Investments basis (i.e., excluding performance of companies whose business models are correlated to hydrocarbon pricing as the principal driver of revenue, specifically, oil and gas exploration and production companies, most midstream investments, oilfield services and mining companies). In 2020, the firm repositioned its energy investing strategy away from investments which are highly correlated to hydrocarbon pricing. The firm determined that businesses with revenues heavily correlated to hydrocarbon prices were inconsistent with the desired return profile of its Global Funds given the inherent volatility of those prices. Warburg Pincus refers to such investments as “Discontinued Energy”. The Industrials team will continue to focus on investments in businesses supported by secular trends to diversify energy sources, create reliable supply and operate businesses more efficiently and sustainably, including such themes as electrification, decarbonization and sustainability. Additional information on the go-forward investment strategy of the Energy Transition & Sustainability team is available upon request. Following the firm’s decision for the Global Funds to transition away from investing in energy companies whose value is highly correlated to hydrocarbon commodity prices, the firm reviewed each of the 99 investments made by the Warburg Pincus energy group since the inception of the firm’s energy program in 1971 (EMWV). The firm distinguished between types of investments the firm does not plan to invest in through the Global Funds, beginning with WPGG 14 (i.e., the first Global Fund to not pursue Discontinued Energy investments), and types of deals the firm may continue to invest in. The firm identified 63 companies representing $13.2 billion of invested capital in discontinued areas of energy investing, and 34 companies representing $3.3 billion of invested capital in areas the firm may continue to pursue. The Ex-Discontinued Energy Investments track record is hypothetical and is intended to illustrate the impact of removing Discontinued Energy Investments from the hypothetical portfolios of the Global Funds, given that, while not limited with respect to their investment mandate, actively investing and future Warburg Pincus funds are not expected to make Discontinued Energy investments. Warburg Pincus believes that it is reasonable to evaluate the performance information included presented on an Ex-Discontinued Energy Investments basis given the expected investment profile for any Warburg Pincus Fund using the methods and assumptions described herein, including those set forth above with respect to subsets of investments.
Comparison with Indices and Benchmarks
Because the Warburg Pincus funds are actively managed and Warburg Pincus has been investing over a long period and in various sectors and geographies, there is no single index or set of indices that are directly comparable to the funds. However, Warburg Pincus believes that the comparisons to public market indices, including on a PME+ basis (as hereinafter described) can provide useful information to investors. Investors should, however, be aware of the limitations of the comparisons. Investments in private equity do not have the same diversification and liquidity profiles as the indices selected for general comparison purposes herein and investors generally cannot invest directly in an index. The MSCI ACWI captures large and mid-cap representation across 23 Developed Markets and 27 Emerging Markets countries. Warburg Pincus is presenting this benchmark given the firm’s global strategy and that it may be used for various comparison purposes by certain investors, although the index does not reflect the impact of the smaller capitalization companies in which Warburg Pincus has invested. Index data was obtained from Datastream as provided by Thomson Reuters. While the aforementioned index is used as a comparison in this Presentation, the comparison of Warburg Pincus returns to any index provides only one approach to comparison of returns and investors should consider comparisons to other indices and benchmarks. The MSCI ACW Financials Index has 483 constituents and captures large and mid-cap representation across 23 Developed Markets and 24 Emerging Markets countries. All securities in the index are classified in the Financials as per the Global Industry Classification Standard (GICS). The MSCI ACWI Healthcare Index has 220 constituents and captures large and mid-cap representation across 23 Developed Markets and 24 Emerging Markets countries. All securities in the index are classified in the Healthcare sector as per the Global Industry Classification Standard (GICS). The MSCI ACWI Information Technology Index has 313 constituents and captures large and mid-cap representation across 23 Developed Markets and 24 Emerging Markets countries. All securities in the index are classified in the Information Technology sector as per the Global Industry Classification Standard (GICS). The MSCI ACWI Industrials Index has 442 constituents and captures large and mid-cap representation across 23 Developed Markets and 24 Emerging Markets countries. All securities in the index are classified in the Industrials sector as per the Global Industry Classification Standard (GICS). The MSCI India Index has 156 constituents and captures large and mid-cap segments of the Indian market. The index covers approximately 85% of the Indian equity universe.
*Developed Markets countries include: Australia, Austria, Belgium, Canada, Denmark, Finland, France, Germany, Hong Kong, Ireland, Israel, Italy, Japan, Netherlands, New Zealand, Norway, Portugal, Singapore, Spain, Sweden, Switzerland, the UK and the US. Emerging Markets countries include: Brazil, Chile, China, Colombia, Czech Republic, Egypt, Greece, Hungary, India, Indonesia, Korea, Kuwait, Malaysia, Mexico, Peru, Philippines, Poland, Qatar, Saudi Arabia, South Africa, Taiwan, Thailand, Turkey and United Arab Emirates.